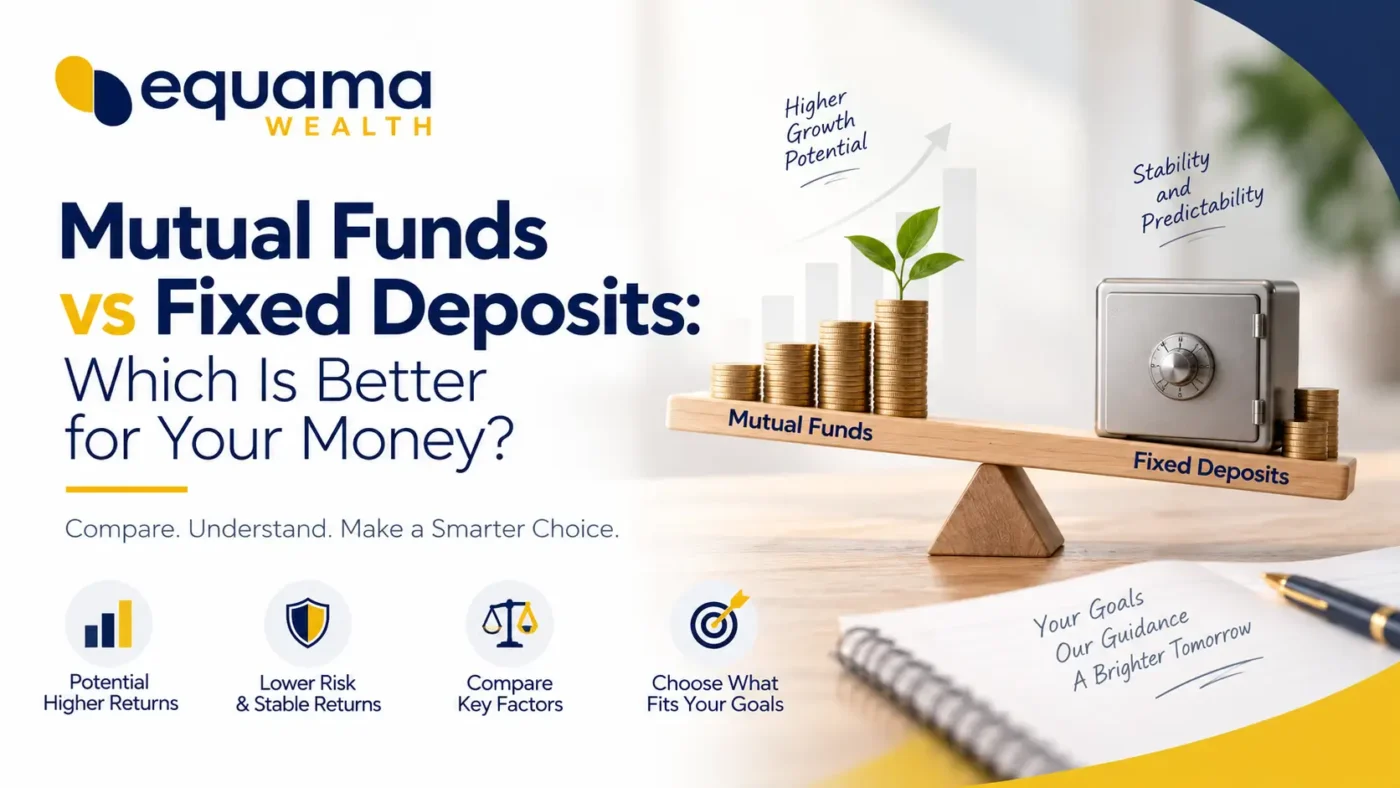
If you’ve grown up in an Indian household, you’ve probably heard two very different pieces of advice: “FD is safe, don’t take risks” from your parents, and “Mutual funds give better returns” from a colleague or a finance influencer. Both are partly right. The real answer depends on what you’re saving for. Let’s break down Mutual Fund Investment and Fixed Deposits across the factors that actually matter.
1. Return Potential
Fixed Deposits offer a fixed, guaranteed interest rate decided upfront — currently most banks offer somewhere in the range of 6-7.5% depending on tenure. You know exactly what you’ll get on maturity.
Mutual funds don’t guarantee anything, but historically, equity mutual funds have delivered higher returns than FDs over long periods, simply because they’re linked to the growth of the stock market. The trade-off is clear: FDs give certainty, equity mutual fund investment gives higher growth potential with no promises attached.
2. Risk Factor
FDs are considered very low risk. Bank deposits are insured up to ₹5 lakh per depositor under the DICGC scheme, which adds a safety layer.
Mutual funds carry market risk — their value moves up and down with the market. Equity funds are more volatile, while debt funds are comparatively steadier but not risk-free either. If protecting your principal is your top priority, FDs win here. If you can handle short-term ups and downs for long-term growth, mutual funds make sense.
3. Liquidity
Need your money back early? FDs usually charge a penalty for premature withdrawal, and you often lose some interest.
Most open-ended mutual funds can be redeemed within 1-3 working days, with no lock-in (except ELSS funds, which have a 3-year lock-in, and closed-ended funds). So if flexibility matters to you, mutual funds generally have the edge.
4. Taxation
This is where things have changed quite a bit, so pay attention here.
FD interest is fully added to your income and taxed as per your income tax slab, every single year — even if you haven’t withdrawn the money. Banks deduct TDS once your yearly interest crosses ₹50,000 (₹1 lakh for senior citizens).
Equity mutual funds are taxed only when you redeem. Long-term gains (held over 12 months) up to ₹1.25 lakh a year are tax-free, and anything above that is taxed at 12.5%. Short-term gains are taxed at 20%.
Debt mutual funds bought after April 2023 no longer enjoy the old tax advantage — they’re now taxed at your slab rate too, similar to FDs.
So for long-term goals, equity-oriented mutual fund investment tends to be more tax-efficient than FDs, mainly because of the yearly exemption and the fact that tax applies only on withdrawal.
5. Beating Inflation
This is often the most overlooked factor. If your FD gives 7% and inflation is running at 5-6%, your real, inflation-adjusted growth is quite thin. Over long periods, equity mutual funds have generally offered better inflation-beating potential, though this comes with market-linked ups and downs along the way, and past trends don’t guarantee future results.
6. Flexibility in Investing
FDs usually need a lump sum upfront. Mutual funds let you start small and stay consistent through a Mutual Fund SIP — investing a fixed amount every month, which suits salaried individuals far better than arranging a large sum at one go.
So, Which One Should You Choose?
Honestly, it’s not really an “either-or” decision. Here’s a simple way to think about it:
- Emergency fund or a goal within 1-2 years → Fixed Deposits make sense, since capital safety matters more than growth here.
- Long-term goals like retirement, a child’s future, or wealth creation over 7+ years → Mutual fund investment, especially through SIPs, generally has more potential to work in your favour.
- A balanced approach → Many investors keep FDs for safety and short-term needs, while building long-term wealth through mutual funds.
The Real Challenge Isn’t Choosing — It’s Getting the Mix Right
Knowing the theory is one thing. Deciding how much of your money should go into FDs versus mutual funds, which fund categories suit your goals, and how to rebalance as your life changes — that’s where most people struggle on their own. DIY decisions often lean too safe (all FD, low growth) or too aggressive (all equity, high stress during market falls), simply because there’s no one reviewing the full picture.
This is exactly the kind of decision a good Mutual Fund Distributor (MFD) helps you get right — balancing safety and growth based on your actual goals, not guesswork. If you’d like help figuring out the right mix for your money, Equama Wealth can guide you through building a plan that fits your financial goals and risk comfort.
Mutual Fund investments are subject to market risks, read all scheme related documents carefully. Fixed Deposit returns mentioned are indicative and subject to change by respective banks. Past performance is not indicative of future returns.